Prediction-Driven Downside-Risk Portfolio Optimization Using Forecast Error-Based Mean Semi-Absolute Deviation
Keywords:
Portfolio Optimization, Downside Risk, Downside Forecast Error, Deep Learning, Return Forecasting, Mean Semi-Absolute Deviation, Prediction-Driven Optimization, LSTM, Transaction Costs, Emerging MarketsAbstract
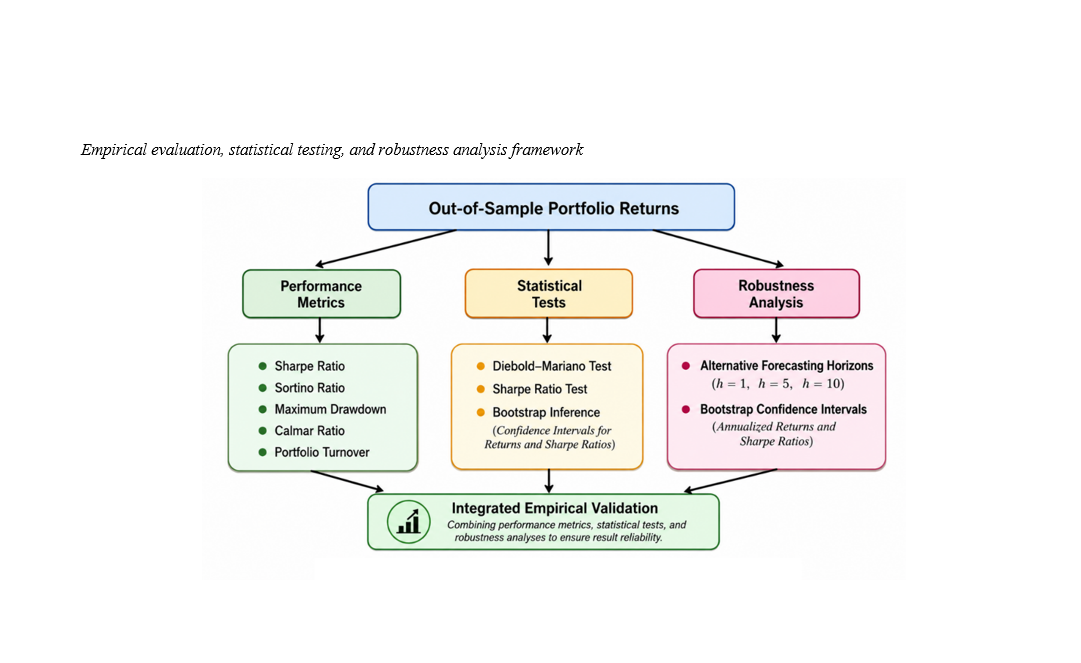
The paper proposes a prediction-driven portfolio framework that explicitly models downside risk arising from systematic over-prediction in return forecasts, departing from conventional predict-then-optimize methods that rely on historical return variability. A new downside forecast error (DSFE) risk measure is embedded into a mean semi-absolute deviation (MSAD) portfolio optimization. Three deep learning models—DMLP, LSTM, and CNN—forecast future OHLCV values, from which return forecasts are derived. Forecasts and portfolio weights are generated within a walk-forward rolling retraining scheme to avoid look-ahead bias. Portfolio risk is defined as the MSAD of portfolio-level downside forecast errors (losses from overly optimistic predictions). Performance is evaluated net of transaction costs and benchmarked against equal-weight, mean–variance, MAD, and CVaR portfolios across multiple risk-adjusted metrics. Using Abu Dhabi Securities Exchange data, Diebold–Mariano tests find no statistically significant difference in predictive accuracy across the three architectures. At the portfolio level, however, the LSTM-based DSFE-MSAD implementation performs best among DSFE-MSAD variants—highest annualized return, Sortino ratio, and terminal wealth. The DSFE-MSAD approach does not uniformly beat all benchmarks: the CVaR portfolio outperforms it on risk-adjusted and terminal-wealth measures in the main one-day-ahead test. The contribution is thus framed as prediction-consistent downside risk integration, not universal outperformance. The framework offers an implementable tool linking predictive uncertainty to downside risk for managers in volatile/emerging markets; transaction costs and turnover are shown to materially affect realized performance, especially for forecast-responsive strategies like DSFE-MSAD. The study introduces a downside-risk measure based on portfolio-level forecast errors, integrated with MSAD optimization under walk-forward, cost-aware conditions—bridging deep-learning forecasting with downside-risk portfolio theory.
Downloads
References
Al-Khasawneh, M. A., Raza, A., Khan, S. U. R., & Khan, Z. (2025). Stock market trend prediction using deep learning approach. Computational Economics, 66(1), 453-484. https://doi.org/10.1007/s10614-024-10714-1
Ararat, Ç., Cesarone, F., Pınar, M. Ç., & Ricci, J. M. (2024). MAD risk parity portfolios. Annals of Operations Research, 336(1), 899-924. https://doi.org/10.1007/s10479-023-05797-2
Arcidiacono, S. G., & Rossello, D. (2022). A hybrid approach to the discrepancy in financial performance's robustness. Operational Research, 22(5), 5441-5476. https://doi.org/10.1007/s12351-022-00707-z
Bae, H., Park, M., Jeon, H., & Kim, W. C. (2026). A decision-focused learning framework for goal-based investing. Quantitative Finance, 1-13. https://doi.org/10.1080/14697688.2025.2596917
Bağcı, M., & Soylu, P. K. (2024). Optimal portfolio selection with volatility information for a high frequency rebalancing algorithm. Financial Innovation, 10(1), 107. https://doi.org/10.1186/s40854-023-00590-3
Ballestero, E. (2005). Mean-semivariance efficient frontier: A downside risk model for portfolio selection. Applied Mathematical Finance, 12(1), 1-15. https://doi.org/10.1080/1350486042000254015
Barro, D., Canestrelli, E., & Consigli, G. (2019). Volatility versus downside risk: Performance protection in dynamic portfolio strategies. Computational Management Science, 16(3), 433-479. https://doi.org/10.1007/s10287-018-0310-4
Bauder, D., Bodnar, T., Parolya, N., & Schmid, W. (2021). Bayesian mean-variance analysis: Optimal portfolio selection under parameter uncertainty. Quantitative Finance, 21(2), 221-242. https://doi.org/10.1080/14697688.2020.1748214
Berger, T., & Fieberg, C. (2016). On portfolio optimization: Forecasting asset covariances and variances based on multi-scale risk models. The Journal of Risk Finance, 17(3), 295-309. https://doi.org/10.1108/JRF-09-2015-0094
Borovička, A. (2022). Stock portfolio selection under unstable uncertainty via fuzzy mean-semivariance model. Central European Journal of Operations Research, 30(2), 595-616. https://doi.org/10.1007/s10100-021-00791-0
Butler, A., & Kwon, R. H. (2023). Integrating prediction in mean-variance portfolio optimization. Quantitative Finance, 23(3), 429-452. https://doi.org/10.1080/14697688.2022.2162432
DeMiguel, V., Garlappi, L., & Uppal, R. (2009). Optimal versus naive diversification: How inefficient is the 1/N portfolio strategy? The Review of Financial Studies, 22(5), 1915-1953. https://doi.org/10.1093/rfs/hhm075
Fischer, T., & Krauss, C. (2018). Deep learning with long short-term memory networks for financial market predictions. European Journal of Operational Research, 270(2), 654-669. https://doi.org/10.1016/j.ejor.2017.11.054
Gârleanu, N., & Pedersen, L. H. (2013). Dynamic trading with predictable returns and transaction costs. The Journal of Finance, 68(6), 2309-2340. https://doi.org/10.1111/jofi.12080
Georgantas, A., Doumpos, M., & Zopounidis, C. (2024). Robust optimization approaches for portfolio selection: A comparative analysis. Annals of Operations Research, 339(3), 1205-1221. https://doi.org/10.1007/s10479-021-04177-y
Gunjan, A., & Bhattacharyya, S. (2023). A brief review of portfolio optimization techniques. Artificial Intelligence Review, 56(5), 3847-3886. https://doi.org/10.1007/s10462-022-10273-7
Karimi Dastgerdi, A., & Zamani Boroujeni, F. (2020). A review of deep learning methods for financial market prediction. Transactions on Data Analysis in Social Science, 2(3), 164-172. https://doi.org/10.47176/TDASS.2020.164
Kingma, D. P., & Ba, J. (2015). Adam: A method for stochastic optimization. International Conference on Learning Representations,
Konno, H., & Yamazaki, H. (1991). Mean-absolute deviation portfolio optimization model and its applications to Tokyo stock market. Management Science, 37(5), 519-531. https://doi.org/10.1287/mnsc.37.5.519
Landsman, Z., Makov, U., Yao, J., & Zhou, M. (2022). Downside risk optimization with random targets and portfolio amplitude. The European Journal of Finance, 28(16), 1642-1663. https://doi.org/10.1080/1351847X.2021.1991421
Law, T., & Shawe-Taylor, J. (2017). Practical Bayesian support vector regression for financial time series prediction and market condition change detection. Quantitative Finance, 17(9), 1403-1416. https://doi.org/10.1080/14697688.2016.1267868
Li, B., Wang, J., Huang, D., & Hoi, S. C. (2018). Transaction cost optimization for online portfolio selection. Quantitative Finance, 18(8), 1411-1424. https://doi.org/10.1080/14697688.2017.1357831
Liu, Y., & Qin, Z. (2012). Mean Semi-Absolute Deviation Model for Uncertain Portfolio Optimization Problem. Journal of Uncertain Systems, 6(4), 299-307.
Lorimer, D. A., van Schalkwyk, C. H., & Szczygielski, J. J. (2024). Portfolio optimisation using alternative risk measures. Finance Research Letters, 67, 105758. https://doi.org/10.1016/j.frl.2024.105758
Markowitz, H. (1952). Portfolio selection. The Journal of Finance, 7(1), 77-91. https://doi.org/10.1111/j.1540-6261.1952.tb01525.x
Michaud, R. O. (1989). The Markowitz optimization enigma: Is 'optimized' optimal? Financial Analysts Journal, 45(1), 31-42. https://doi.org/10.2469/faj.v45.n1.31
Mohammadi, S., & Mansourfar, G. (2022). The Effect of Financial Data Noise on the Long-Term Co-Movement of Stock Markets. Transactions on Data Analysis in Social Science, 4(1), 9-21. https://doi.org/10.47176/TDASS/2022.9
Petrozziello, A., Troiano, L., Serra, A., Jordanov, I., Storti, G., Tagliaferri, R., & La Rocca, M. (2022). Deep learning for volatility forecasting in asset management. Soft Computing, 26(17), 8553-8574. https://doi.org/10.1007/s00500-022-07161-1
Pla-Santamaria, D., & Bravo, M. (2013). Portfolio optimization based on downside risk: A mean-semivariance efficient frontier from Dow Jones blue chips. Annals of Operations Research, 205(1), 189-201. https://doi.org/10.1007/s10479-012-1243-x
Rockafellar, R. T., & Uryasev, S. (2000). Optimization of conditional value-at-risk. Journal of Risk, 2, 21-42. https://doi.org/10.21314/JOR.2000.038
Tang, Y., Song, Z., Zhu, Y., Yuan, H., Hou, M., Ji, J., Tang, C., & Li, J. (2022). A survey on machine learning models for financial time series forecasting. Neurocomputing, 512, 363-380. https://doi.org/10.1016/j.neucom.2022.09.003
Tu, X., & Li, B. (2024). Robust portfolio selection with smart return prediction. Economic Modelling, 135, 106719. https://doi.org/10.1016/j.econmod.2024.106719
Yao, H., Huang, J., Li, Y., & Humphrey, J. E. (2021). A general approach to smooth and convex portfolio optimization using lower partial moments. Journal of Banking & Finance, 129, 106167. https://doi.org/10.1016/j.jbankfin.2021.106167
Yilmaz, F. M., & Yildiztepe, E. (2024). Statistical evaluation of deep learning models for stock return forecasting. Computational Economics, 63(1), 221-244. https://doi.org/10.1007/s10614-022-10338-3
Yue, W., Wang, Y., & Xuan, H. (2019). Fuzzy multi-objective portfolio model based on semi-variance-semi-absolute deviation risk measures. Soft Computing, 23(17), 8159-8179. https://doi.org/10.1007/s00500-018-3452-y
Zhang, C., Sjarif, N. N. A., & Ibrahim, R. (2024). Deep learning models for price forecasting of financial time series: A review of recent advancements: 2020-2022. Wiley Interdisciplinary Reviews: Data Mining and Knowledge Discovery, 14(1), e1519. https://doi.org/10.1002/widm.1519
Zhou, L., Chen, X., & Tang, X. (2025). Comparative performance of machine learning-selected portfolios from dynamic CSI300 constituents: Forward vs. backward adjusted stock prices. Applied Intelligence, 55(3), 176. https://doi.org/10.1007/s10489-024-06107-4
Publication Timeline
- Submitted
- Revised
- Accepted